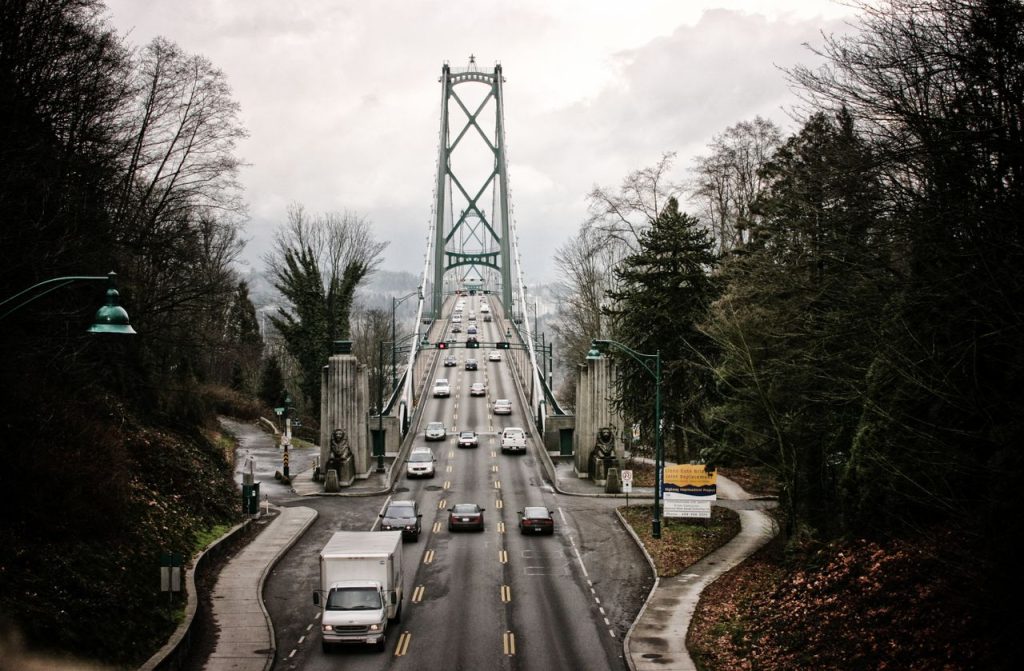
Driving in British Columbia offers some of the most beautiful routes in the world, but navigating the costs of auto insurance can sometimes feel less scenic. With ICBC managing basic auto coverage across the province, many drivers assume their premiums are entirely out of their control. However, understanding exactly how your rates are calculated puts you firmly in the driver’s seat when it comes to managing your costs.
Start by evaluating your daily driving habits and your long-term record. ICBC uses a “Driver Factor” to determine your premium, which represents your risk on the road. The longer you drive without an at-fault crash, the better your factor becomes. Making informed choices about how often you drive, the safety features of your vehicle, and your adherence to traffic rules can translate into significant long-term savings.
Your driving record is your most valuable financial asset on the road. Consistent, safe driving, combined with a strong understanding of BC’s traffic laws, is the most direct route to lower insurance premiums.
For newer drivers, the journey through the Graduated Licensing Program (GLP) is a critical time. Maintaining a pristine driving record while holding a learner’s or novice permit lays the foundation for future savings. Taking the time to deeply understand road signs, right-of-way rules, and hazard perception doesn’t just help you pass your road tests it actively protects your wallet. BC’s Graduated Licensing Program changes on October 19, 2026. Drivers should check ICBC’s current licensing guidance for the requirements that apply to them.
Actionable steps to reduce your premium costs
When choosing or renewing your auto insurance, it’s important to look beyond just the base rate. While ICBC sets the foundation, there are several variables and discounts you can control. Take the time to assess your vehicle usage and ensure you are claiming every discount you qualify for.
- Maintain a clean driving record: Years of crash-free driving build up your Driver Factor, offering the most substantial discount on your premium.
- Upgrade your license status: Safely progressing from a Class 7 (N) to a full Class 5 license removes driving restrictions and positively impacts your premium standing.
- Track your mileage: Eligible annual policies may qualify for a 10% Basic distance-based discount when the vehicle is driven less than 5,000 km per year. Eligible ICBC Optional coverage may also qualify for a distance-based discount when the vehicle is driven less than 15,000 km per year, subject to ICBC’s current eligibility and odometer-reading requirements.
- Leverage vehicle safety features: Vehicles equipped with factory-installed Autonomous Emergency Braking (AEB) systems are eligible for specific ICBC discounts.
- Brush up on traffic laws: Avoiding penalty points and traffic tickets keeps your record clean and your insurance costs highly manageable.
There are various optional coverages available to supplement your basic ICBC plan, such as extended third-party liability, collision, and comprehensive coverage. Researching each type carefully ensures you aren’t leaving yourself vulnerable to out-of-pocket costs. As your insurance partner, I can help you review your current ICBC policy, compare optional features, and secure the right protection for your vehicle.
